TAXOCRATE (Pvt) Limited

Income tax legal services

Income Tax Lawyers In Pakistan — Income Tax Experts for Accurate Filing

FBR IRIS Filing and Documentation Review

Senior Tax and Legal Practice Since 1985

Income tax lawyers in Pakistan for FBR notices, assessment disputes, appeals and recovery review. Discuss your documents and deadlines with Taxocrate.

FBR NoticesAssessmentsIncome Tax AppealsRecovery MattersWithholding Disputes

Tax Consultation and Document Review

Document Review, FBR IRIS Filing and Senior Tax-Law Oversight

Karachi DHA Phase 7 Office: 76C, Mezzanine Floor, Main Jami Commercial, Phase 7, DHA, Karachi, Pakistan · +92 331 6644789

Karachi Registered Head Office: M-96, Mezzanine Floor, Munir Mobile Mall, Block 17, Gulistan-e-Jauhar, Karachi, Pakistan · +92 331 6644789

Income tax lawyers in Pakistan: illustrative legal case-file and evidence review desk
Income Tax Lawyers — illustrative tax legal-review scene. Generated illustration; not an actual office or client record.

Income Tax Lawyers In Pakistan — Income Tax Experts for Accurate Filing: Consultation

Pakistan Document Review and Service Enquiries

Speak with our professional team about Income Tax Lawyers in Pakistan and schedule an appointment. Contact our team to confirm the appropriate office city and appointment arrangements. Office directions are shared via WhatsApp when your appointment is confirmed.

Call +92 331 6644789

Pakistan-Wide Tax Team

Tax Return Specialists With Senior Legal and Corporate Tax Review

Taxocrate handles tax-return, FBR and corporate-tax work across Pakistan through an experienced professional team. The team coordinates document preparation, tax analysis and legal review according to the scope agreed for each client.

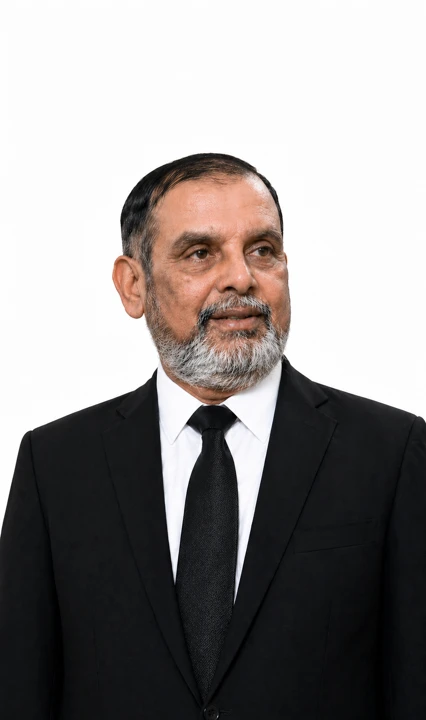
Syed Mohsin Ali Shah, Senior Corporate And Taxation Lawyer · Tax Return Specialist — professional portrait accompanying Income Tax Lawyers in Pakistan guidance

Syed Mohsin Ali Shah

Senior Corporate And Taxation Lawyer · Tax Return Specialist

40+ Years Of Professional Tax And Legal Experience

Syed Mohsin Ali Shah provides senior review for income-tax returns, FBR compliance, corporate taxation, tax notices, business structuring and higher-risk tax matters across Pakistan.

Professional Profile
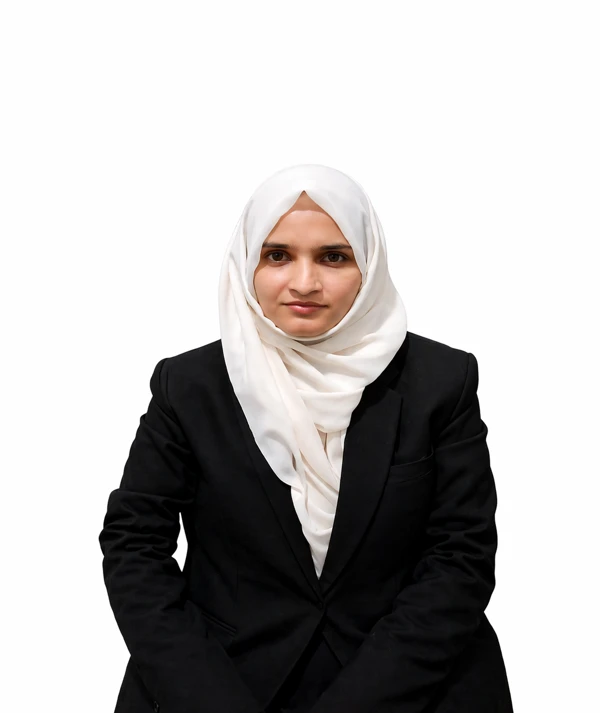
Sobia Mohsin, Advocate · Corporate Taxation Consultant · Tax Return Specialist — professional portrait accompanying Income Tax Lawyers in Pakistan guidance

Sobia Mohsin

Advocate · Corporate Taxation Consultant · Tax Return Specialist

10+ Years Of Professional Tax And Corporate Experience

Sobia Mohsin works on tax-return preparation and review, corporate taxation consultation, documentation, compliance coordination and client tax matters across Pakistan.

Professional Profile

Income Tax Lawyers In Pakistan By Taxocrate Since 1985

Income Tax Lawyers In Pakistan for FBR Representation and Tax Disputes

Income tax lawyers in Pakistan assist taxpayers when an FBR matter requires legal interpretation, a response to a notice, assessment review, appeal strategy, recovery defence, withholding-tax analysis or representation beyond routine annual return filing. Taxocrate combines tax compliance and legal support so the filed record and the legal position can be reviewed together.

Received an FBR notice, order or tax demand? Preserve the complete document, note the deadline and obtain a provision-specific review before filing a reply, appeal or payment response.

Income Tax Lawyers: Routine Tax Filing Vs Contested FBR Matter

IssueRoutine ComplianceContested FBR Matter
Typical workReturn filing, wealth reconciliation, NTN/ATL reviewNotice, assessment, appeal, recovery or disputed interpretation
Primary focusAccurate and timely complianceLegal position, evidence, deadlines and representation
RecordsIncome, banking, withholding and wealth recordsComplete FBR notice/order plus filing and evidentiary record
Professional roleTax compliance professionalIncome tax lawyer / legal representative where appropriate

Income Tax Lawyers In Pakistan for FBR Notices and Legal Review

Income tax lawyers in Pakistan should begin an FBR matter with the actual notice, order or communication rather than a generic explanation of tax law. The statutory provision, tax year, date of service, response deadline, information demanded and possible consequence should all be identified before a reply is drafted.

Income tax lawyers in Pakistan also need to understand the taxpayer's existing record. Returns, wealth statements, accounts, bank statements, withholding information, property records and earlier correspondence can affect the legal position. A response that contradicts the filed record can create avoidable difficulty even where the taxpayer has a valid substantive argument.

Income Tax Lawyers In Pakistan Vs Routine Tax Filing

Income tax return filing and tax litigation are different assignments. Routine filing focuses on preparing accurate annual compliance through FBR IRIS, reconciling income, tax deductions and wealth, and retaining supporting records. Legal representation becomes more important when FBR issues a contested notice, assessment, penalty, recovery action or another decision that can affect rights, liability or deadlines.

Routine Income Tax ComplianceIncome Tax Legal Representation
Annual return filingFBR notice response
Wealth statement reconciliationAssessment and amended assessment review
NTN/profile and ATL reviewAppeal and appellate strategy
Withholding credit reviewRecovery and tax-demand disputes
Tax payment and record organisationContested legal interpretation

Income Tax Lawyers In Pakistan for Assessments and Amended Assessments

Income tax lawyers in Pakistan handling an assessment matter should review the legal basis of the proceeding together with the factual and accounting record. The question is not only whether FBR has proposed additional tax; it is also whether the correct statutory power has been used, whether the relevant facts have been understood and whether the taxpayer has documentary evidence to support the declared position.

Where the case involves business income, banking, property, withholding or wealth, the underlying figures should be traced to source documents. A strong legal response is more persuasive when the evidence is organised and the taxpayer's position is internally consistent.

Income Tax Lawyers In Pakistan for Income Tax Appeals

Income tax lawyers in Pakistan preparing an appeal should analyse the impugned order, the issues decided, the evidence considered or ignored, the statutory provisions involved, the limitation period and the appropriate appellate forum. Grounds of appeal should focus on material errors rather than simply repeat every disagreement with FBR.

The appeal file should include the complete order, notices, replies, supporting evidence, returns, wealth statements, payment records and any other material relevant to the disputed findings. The chronology of the proceeding can be important where the taxpayer challenges service, opportunity of hearing, factual assumptions or legal interpretation.

Income Tax Lawyers In Pakistan for Appellate Evidence and Record Preparation

Income tax appeals are easier to manage when the record is indexed by issue. Bank statements, invoices, contracts, withholding certificates, property papers, tax payment CPRs and prior correspondence should be organised so that the legal submission can point to the evidence supporting each factual proposition.

Income Tax Lawyers In Pakistan for Tax Demand and Recovery Matters

Income tax lawyers in Pakistan can review tax-demand and recovery matters by first identifying the underlying order, the status of any appeal or other remedy, the amount demanded, payments already made and the procedural step taken by FBR. Recovery should not be analysed separately from the order that created the demand.

Where a taxpayer has a pending challenge or another legal basis relevant to recovery, the supporting record should be assembled promptly. Deadlines matter, and delay can reduce procedural options even where the taxpayer has a substantial argument on the merits.

Income Tax Lawyers In Pakistan for Withholding Tax Disputes

Income tax lawyers in Pakistan frequently deal with disputes about withholding tax. The issues can include whether the taxpayer was required to deduct or collect tax, which statutory section applied, the correct rate, taxpayer category, ATL position, exemption or reduced-rate treatment, and whether the amount is adjustable or otherwise treated under the law.

The transaction should be identified before the rate is debated. Contracts, invoices, payment evidence, taxpayer status and the applicable tax-year law should be reviewed together. A percentage copied from an old rate card is not a substitute for legal analysis of the transaction.

See FBR Withholding Tax in Pakistan and FBR Withholding Tax Rates 2026-27.

Income Tax Lawyers In Pakistan for FBR Tax Refund Disputes

Income tax lawyers in Pakistan may become involved where an income tax refund moves beyond routine filing into a disputed or legally complex matter. The filed return, refund amount, tax credits, withholding evidence, IRIS application history, limitation position and any FBR correspondence should be reviewed as one file.

A refund claim should be supported by the underlying tax payment or deduction evidence. If the return itself is incorrect, the appropriate return-correction or revision issue should be examined before the taxpayer relies on the refund application.

See Income Tax Refund from FBR.

Income Tax Lawyers In Pakistan for Wealth Statement and Source-of-Funds Issues

Income tax lawyers in Pakistan can also assist when FBR questions the source of funds, wealth reconciliation or a material asset. The taxpayer should identify the transaction, acquisition date, payment trail, prior wealth position and the source relied upon to explain the asset or investment.

Gifts, loans, inheritances, remittances, asset disposals and business capital movements should be supported by evidence appropriate to the facts. A narrative inserted only to balance a wealth statement may not be sufficient if the matter later becomes contested.

Income Tax Lawyers In Pakistan for Business and Corporate Tax Matters

Income tax lawyers in Pakistan advising businesses should understand the taxpayer's legal structure and commercial activity. Sole proprietors, AOPs and companies can have different filing, accounting and withholding implications. Corporate tax matters can also interact with SECP records, shareholder or director transactions, sales tax, payroll and sector-specific regulation.

When a tax dispute arises from business records, the legal team should review the accounts and transaction evidence instead of treating the case as a purely theoretical interpretation. Tax litigation often turns on both the law and the quality of the factual record.

Income Tax Lawyers In Pakistan for Salaried and Individual Taxpayers

Income tax lawyers in Pakistan are not limited to corporate cases. Individual taxpayers can face notices concerning wealth, property, bank activity, tax credits, non-filing or unexplained transactions. A salaried taxpayer may also have rent, investments, capital gains or other income that affects the legal and factual position.

Where the matter is still routine annual compliance, see Income Tax Return Filing in Pakistan. Legal representation should be matched to the actual risk and stage of the matter.

Income Tax Lawyers In Pakistan: Documents for A Legal Consultation

  • The complete FBR notice, order, demand or other communication, including attachments.
  • Evidence of service and the response or appeal deadline where relevant.
  • Income tax returns and wealth statements for the relevant and connected years.
  • Previous replies, applications, orders and correspondence with FBR.
  • Bank statements and material transaction records.
  • Business accounts, invoices, contracts and expense evidence where relevant.
  • Property, investment, vehicle or remittance documents relevant to the issue.
  • Withholding certificates, CPRs and tax-payment evidence.
  • Any professional or accounting working papers that explain the disputed figures.

Income Tax Lawyers In Pakistan: Common Mistakes Before Legal Review

  • Replying to a notice before identifying the statutory provision and deadline.
  • Submitting a generic explanation that does not answer the allegation.
  • Changing a return or wealth statement without reviewing the effect on the dispute.
  • Providing figures inconsistent with bank records, accounts or prior filings.
  • Relying on an old tax rate or outdated legal summary.
  • Waiting until the appeal or response deadline is about to expire before collecting the record.
  • Sending incomplete screenshots instead of the full notice or order.

Income Tax Lawyers In Karachi, Islamabad, Rawalpindi and Lahore

Income tax lawyers in Pakistan can review many FBR matters remotely because returns, notices and much of the tax record are electronic. Forum, jurisdiction and appearance requirements still depend on the specific proceeding. Taxocrate maintains contact routes for Karachi, Islamabad, Rawalpindi and Lahore and can identify the appropriate handling route after the document and forum are reviewed.

For a dedicated Karachi page, see Income Tax Lawyers in Karachi.

Income Tax Lawyers In Pakistan By Taxocrate

Income tax lawyers in Pakistan by Taxocrate work within a broader tax, corporate and regulatory practice. That structure is useful because a contested matter can require both legal analysis and a detailed understanding of the taxpayer's annual compliance record, accounting information and FBR history.

Taxocrate's professional practice dates to 1985. The approach is to identify the exact legal issue, protect deadlines, organise the evidentiary record and keep the legal position consistent with the returns and documents already on file.

Income Tax Lawyers In Pakistan: Practical Next Step

If you have an FBR notice or order, send the complete document rather than only a screenshot of the heading. Identify the tax year, note the deadline and collect the connected return, wealth statement and key evidence. If no dispute exists and the requirement is only annual compliance, use the appropriate income tax return filing service instead of treating routine work as litigation.

Income Tax Lawyers: An Evidence Plan for Each Issue

List each disputed finding and the document that supports your response. For a banking entry, locate the statement, transfer evidence and explanation of the underlying transaction. For a business expense, connect the invoice with the payment and accounting entry. If a supporting record is missing, identify that gap before approving the submission. A short index with consistent page numbers helps the reviewer follow the evidence and distinguish an established fact from an assertion that still needs support.

Income Tax Lawyers: Consultation Scope and Handover

Agree whether the engagement covers an initial opinion, notice reply, appeal preparation, hearing or a separate recovery application. A fee quotation should distinguish professional charges from official fees and other expenses. Ask who will approve the factual statement, sign the necessary documents and monitor the next date. At handover, retain the final submission, filing evidence, annexure index and the team's explanation of outstanding work. An initial document review is useful, but it should not be mistaken for completion of every procedural step.

Income Tax Lawyers: Official Appeal Guidance

FBR's income tax appeal guidance provides an introduction to dispute remedies. The current law, order, forum and service record should be reviewed for the individual case before a procedural route or deadline is confirmed. Related professional resources include Pakistan Tax and Income Tax Lawyers.
Official Sources and Related Tax Resources

FBR Return Filing Guidance · FBR IRIS · Pakistan Tax · Income Tax Lawyers

Frequently Asked Questions

What Do Income Tax Lawyers In Pakistan Handle?

Income tax lawyers review contested matters involving FBR notices, assessments, appeals, recovery, withholding and disputed refunds. The first task is to identify the actual issue from the complete communication and connected records. Some enquiries need a short opinion; others require preparation of a response or representation at a defined procedural stage. Taxocrate discusses the scope after examining the documents. Share the taxpayer category, relevant years and approaching dates so the team can distinguish legal work from bookkeeping, annual compliance or a separate registration question before quoting the assignment.

When Should I Contact An Income Tax Lawyer?

Contact the team promptly when an FBR document raises a disputed allegation, demand or procedural deadline. Send every page and attachment rather than only the heading. Explain when and how you received it and whether any reply has already been submitted. Early review allows time to locate evidence and examine the available route. Do not wait for complete accounts before sharing an urgent notice: identify the missing records at the start. The initial consultation should establish the immediate next step and any additional information required for a reliable opinion.

Is Return Filing The Same As Tax Legal Representation?

Return preparation focuses on annual declarations, tax calculations and supporting financial records. Legal representation concerns a disputed issue, procedural remedy or response to an authority. The two assignments may overlap when a notice questions figures already filed, but their deliverables should be agreed separately. Provide the actual submitted return and acknowledgement during a legal review. A filing service quotation should not be assumed to include appeals, hearings or recovery applications. Taxocrate can coordinate the record while explaining which compliance and legal tasks form part of the agreed work.

What Should I Send After Receiving An FBR Notice?

Send the complete notice, annexures, available service evidence and the connected returns or statements. Add earlier correspondence and records directly relevant to the allegation. A banking question may need account statements; a business expense question may need invoices and payment evidence. Organise documents by taxpayer and year. Explain which items remain unavailable and whether another consultant has already responded. The lawyer can then identify the provision, factual question and preparation needed. Avoid replacing the original documents with an informal summary, because omitted wording can materially change the issue being reviewed.

How Is An FBR Notice Reply Prepared?

Preparation begins by separating the allegations, requested information and dates in the notice. The team compares those points with the filed record and supporting evidence, then develops a response that addresses each material issue. The taxpayer should confirm the factual explanation before submission. Number the annexures and retain the final version with filing evidence. If information is missing, discuss the procedural options for that situation rather than invent an answer. A reply copied from another taxpayer's matter may overlook the actual transaction, year or legal basis raised in your notice.

Can Income Tax Lawyers Review An Assessment Order?

An assessment review examines the order, the record considered, the reasoning used and the amount determined. Provide the preceding notices, replies and evidence as well as the final document. The lawyer can compare the findings with the taxpayer's position and identify issues that require factual correction or legal challenge. Do not treat the demand figure as the entire case: the route and time position also require attention. The review should explain the available next step and the supporting records needed before an appeal or another application is authorised.

How Is An Income Tax Appeal Planned?

Appeal planning starts with the complete order, relevant service record and current procedural rules. The reviewer identifies the available forum, material grounds and evidence supporting each ground. A broad statement that the taxpayer disagrees is less useful than an explanation of the specific factual or legal error. Keep the original proceedings file intact, including replies and annexures already submitted. Discuss the filing requirements and representation scope before preparation. Taxocrate can organise the case record, but the precise route and applicable limitation must be checked against the individual order and current law.

Does Filing An Appeal Automatically Resolve Recovery?

Do not assume that an appeal by itself answers every recovery question. The demand, pending proceedings, any separate application and the applicable legal framework should be reviewed together. Send recovery correspondence immediately and explain payments or adjustments already made. The team needs to know whether a request for interim protection has been filed and what decision, if any, was received. Keep copies of all relevant orders. A practical opinion should identify the next procedural step and outstanding conditions rather than promise that submitting one document necessarily prevents further collection action.

How Are Withholding Tax Disputes Reviewed?

Identify the transaction, date, parties and payment trail before discussing the percentage applied. The legal issue may concern the obligation to deduct, the taxpayer category, status evidence, exemption position or treatment of the amount collected. Provide contracts, invoices, deduction records and the calculation used. An old rate chart cannot establish the correct treatment for every later transaction. The lawyer should explain which provision and facts support the advice. Keep registration and ATL evidence separate so a registration certificate is not used as a substitute for a dated status check.

Can A Refund Enquiry Require A Tax Lawyer?

A refund enquiry may require legal review when the amount, supporting credit, application history or FBR decision is disputed. Supply the filed return, withholding and payment evidence, application copies and correspondence. The team should check that the claimed amount can be traced to the underlying record. If an error exists in the return, discuss the appropriate correction route before relying on the claim. A professional engagement should identify whether it covers calculation, application follow-up, response preparation or a contested remedy. No refund amount or completion date should be assumed without reviewing the case.

Should I Revise A Return Before Legal Consultation?

A material revision should be considered with its effect on the existing proceeding and evidence. Share the filed version, the proposed correction and the reason for the change. Identify whether FBR has already raised the point and whether earlier statements would become inconsistent. The legal and accounting teams can then review the appropriate course under the applicable rules. Preserve the original and revised working files separately. Do not alter figures simply to match an allegation without understanding the underlying facts. The consultation should establish the problem before selecting a correction procedure.

How Are Wealth and Source-of-Funds Questions Examined?

Start with the asset or transaction being questioned, its date, value and payment record. Connect the explanation with prior wealth statements and evidence of the source relied upon. A loan, gift, disposal or remittance should be reviewed using records appropriate to that transaction. The team may need accounting reconciliation as well as legal analysis. Explain any missing evidence before a response is drafted. A narrative created only to balance figures may not answer the question raised by FBR. Keep the calculation and supporting documents together so the explanation can be checked.

Can Salaried Individuals Need Income Tax Lawyers?

An employment record does not prevent a separate tax question about property, banking, investments, credits or wealth. If an individual receives an FBR communication, the review should address its actual allegation rather than assume salary deductions settle the matter. Provide employer certificates, the submitted return and documents concerning the disputed transaction. Explain other income and material asset movements relevant to the year. The team can distinguish routine return work from a contested issue. A legal consultation becomes more useful when the taxpayer shares the complete financial context rather than only the salary figure.

Can Companies and Aops Obtain Tax Legal Assistance?

Companies and associations of persons can require review of assessments, withholding, accounts, recovery or disputed interpretation. Provide the entity's identifier and records separately from those of directors or partners. Identify the authorised person coordinating the assignment and approving factual statements. Business transactions may need contracts, ledgers and payment evidence as well as tax returns. The engagement should clarify whether accounting reconstruction is included or supplied by another professional. Taxocrate can coordinate the legal review with the business's existing advisers while maintaining a clear distinction between personal and entity matters in the file.

Can An Overseas Client Arrange A Remote Review?

An initial document review can often be coordinated remotely using copies of the relevant records. Explain the client's location, available authorised contact and any approaching procedural date. The team should examine whether the specific forum or assignment requires original documents, formal authority or an appearance. Remote communication alone does not establish that every stage can be completed without additional arrangements. Keep a clear record of approvals and final submissions. Taxocrate can discuss the practical handling route after reviewing the document, taxpayer category and nature of the requested representation for the matter.

Can Taxocrate Assist Clients Outside Karachi?

Taxocrate maintains contact routes for clients across Pakistan, and the initial legal record can be reviewed before the handling arrangement is confirmed. Share the authority issuing the document, the relevant location and the procedural stage. Jurisdiction and appearance requirements should be examined for the particular case. A national service page should not imply that every proceeding is handled identically in every city. The quotation can identify who coordinates the matter and which work is included. For a Karachi enquiry, the dedicated local page provides consultation details and the relevant contact route.

How Are Tax Legal Fees Quoted?

A useful quotation identifies the work requested: initial opinion, notice reply, appeal preparation, hearing or recovery review. Explain the number of years, documents and issues involved before asking for a price. Professional fees should be distinguished from official charges and other expenses. Confirm whether accounting assistance, additional hearings or later proceedings require separate instruction. The scope should state the expected deliverables and the client's approval responsibilities. A short document review and a contested case with extensive evidence can require different work, so one advertised amount should not be assumed to cover every stage.

What If An Earlier Reply Was Filed By Another Adviser?

Provide the actual reply, annexures and submission evidence alongside the notice or order. Explain who prepared it and which factual information was supplied at the time. The new reviewer needs to understand the position already taken before recommending another submission. Keep the original record intact, even if you now disagree with parts of the response. Identify any supporting evidence that was available but omitted. Taxocrate can assess the next step from the existing file; replacing the history with a new summary may obscure statements or procedural events important to the matter.

What Should I Receive After A Tax Legal Assignment?

Retain the agreed opinion or final submission, annexure index, filing evidence and any order received during the assignment. Ask for a clear explanation of completed work and the next procedural date or unresolved issue. A notice reply does not necessarily complete a later assessment or appeal. Keep draft calculations separately from the final version relied upon. The handover should identify further work requiring instruction and any records still needed from you. This allows the taxpayer, accountant and another professional to understand the current position without reconstructing the case from messages.

Can Income Tax Lawyers Guarantee A Successful Outcome?

A responsible assessment depends on the law, evidence, procedure and decision-making authority involved. The initial review can identify strengths, gaps and available steps, but it should not promise that every demand will disappear or every appeal will succeed. Provide accurate facts and disclose earlier communications so the advice addresses the complete record. Ask the team to explain what supports its proposed approach and which matters remain uncertain. The engagement should focus on defined professional work, timely preparation and an organised evidentiary record rather than a result promised before the file has been examined.

Need advice? Call now: +92 331 6644789